Trading income tax
12.5%
25% for non-trading income; special rules may apply
Connect with an English-speaking market for technology, specialist services and life-sciences supply chains.
Start your journey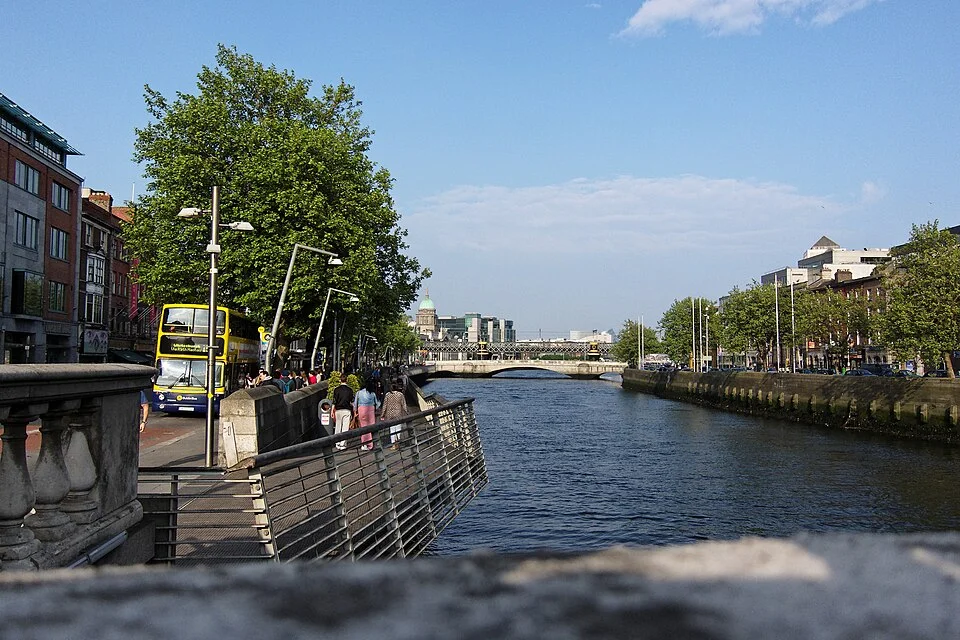
12.5%
25% for non-trading income; special rules may apply
23%
Reduced rates and exemptions depend on the supply
EUR
Euro
Director rules
EEA-resident director, qualifying exemption or bond
The Commission’s May 2026 forecast puts modified domestic-demand growth at 2.8% for 2026. Headline GDP is distorted by multinational exports. Assess demand in your specific sector alongside staffing, premises and operating costs.
European Commission · May 2026 forecast (opens in a new tab)Start with a defined opportunity, then assess the route to market.
Explore customer and delivery partnerships for software, data and specialist business services.
IDA · sectors (opens in a new tab)Identify relevant buyers for specialist equipment, components or services, then establish the procurement and quality requirements.
Compare serving customers from India with a local presence, based on contracts, staffing and the substance your business needs.
Taxes, establishment and the detail behind a commercial decision.
Trading income is generally taxed at 12.5%; non-trading income at 25%. The effective result depends on activities and applicable rules, including those for large groups.
Irish Revenue · corporation tax (opens in a new tab)Standard VAT is 23%. Model staffing, premises, insurance and professional fees separately from corporate tax.
EU VAT rates (opens in a new tab)An Irish company generally needs an EEA-resident director, a qualifying exemption or a bond with €25,000 coverage. That figure is coverage, not the bond’s purchase price.
Companies Registration Office (opens in a new tab)Registering a company does not grant permission to live or work in Ireland. Assess the founder’s immigration route alongside the proposed business activity.
Check your product’s HS code, origin, customs duties and applicable standards. Include freight, import VAT and distributor margins in the landed cost before choosing a route to market.
EU Access2Markets (opens in a new tab)Headline tax rates are not the total cost of operating. Reduced rates, sector rules, payroll obligations and large-group regimes may apply. Incorporation and permission to live or work are separate processes.
Validate demand, establish the full cost of serving clients and select a practical entry route. Europath can help connect your commercial objectives with market-entry and visa guidance.
Guidance that starts with your goals.
Define your market, customers and commercial objectives.
Prepare the relevant registrations and visa applications for your chosen route.
Move forward with your business and trade connections.
No. Company registration, ownership, residence and permission to work are distinct matters. The appropriate immigration route depends on your nationality, intended activity and eligibility.
That depends on your product or service, customers, budget and staffing needs. A distributor, commercial partnership, branch or locally established company may serve different objectives.
Tell us about your business. We’ll help you explore the next step.
Dublin · River Liffey · Barcex · CC BY-SA 3.0. Resized, WebP format; cropped to fit the layout. The photograph retains its stated licence.
Last reviewed · Guidance for applicants and businesses based in India.